
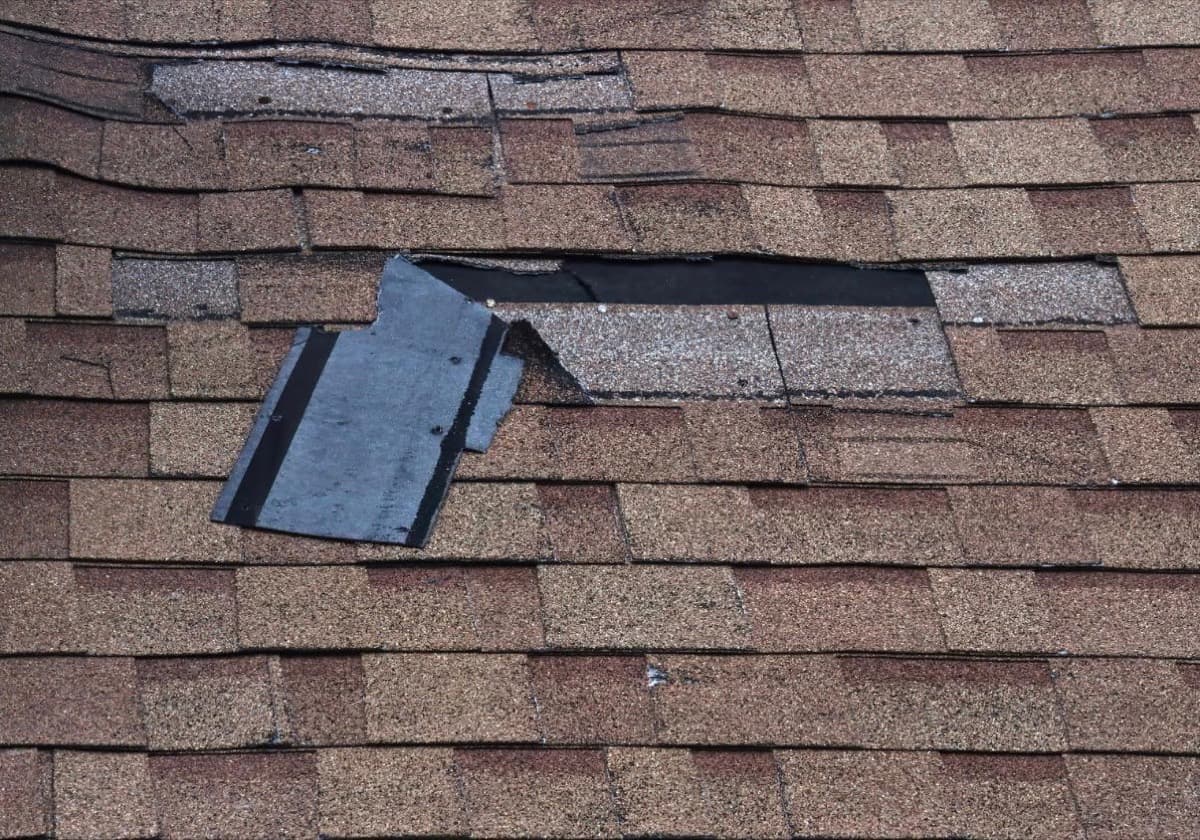
Storm & Hail Damage
Iowa weather is unpredictable. When disaster strikes, you need a local contractor you can trust, not a storm chaser.
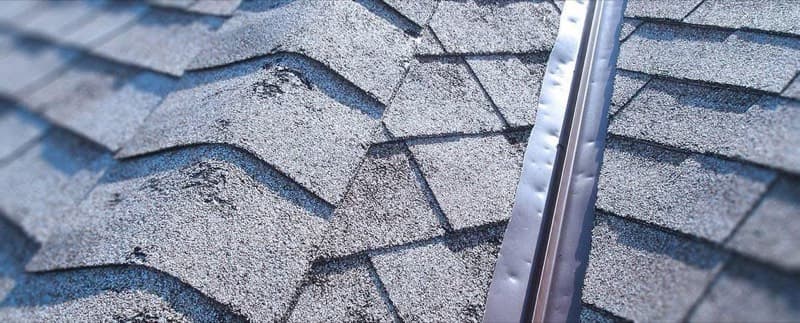
Our Expertise
What should you do after hail or wind damages your roof?
Stay off the roof and record visible damage from a safe location. Bakeris Roofing provides free qualifying storm damage inspections in Des Moines and Central Iowa, with photos, a written construction scope, and an estimate. Emergency tarping depends on safe access and crew availability. Ask your carrier or agent about coverage, deductibles, and claim deadlines; an inspection does not guarantee insurance coverage.
Unlike out-of-state storm chasers who disappear after cashing your check, Bakeris Roofing has been serving Des Moines and Central Iowa since 1990. We're your neighbors, and we're not going anywhere.
From the first inspection through final cleanup, we build the strongest construction record the facts support: a full exterior inspection, labeled photo evidence, impact measurements, a written repair scope and estimate, emergency protection when needed, adjuster-site attendance when requested, and clear construction answers that keep the roofing work moving.
Iowa hail season runs roughly mid-April through mid-September, with peak activity in May, June, and July. Polk and Dallas counties average 2-3 hail events per year that produce stones large enough to damage shingles. Wind events with sustained gusts above 60 mph happen multiple times each season. The damage isn't always obvious from the ground, which is why a professional inspection within a few weeks of a storm is the right call. Claim deadlines vary by policy and insurer, so contact your carrier or agent promptly.
When an adjuster comes out, they're looking for specific markers: bruised or fractured shingles (you can sometimes feel the soft spot where hail impacted), exposed mat where granules have been knocked off, dented gutters and downspouts, dented metal flashing and vent caps, and damage to other softer parts of the home like siding and AC condenser fins. We document all of these with photos and measurements so you have a complete record to share with your insurance company.
A claim doesn't mean you need a full roof replacement. Sometimes the construction scope is a targeted repair, sometimes only damaged slopes require work, and sometimes the documented condition calls for full replacement. The insurer determines what it covers. We explain the construction options after you and your insurer determine coverage. We don't push for replacements that aren't justified.
What's Included
The Bakeris Difference
Go deeper
Iowa Hail Damage Insurance Claims: Step by Step (2026)
How the process works in Iowa: inspection first, the filing window, what adjusters look for, and how supplements happen.
Read the guide →What To Do After a Hail Storm Hits Your Roof
The order of operations in the first 48 hours, and the mistakes that make damage harder to prove later.
Read the guide →Common Local Searches We Help With
Homeowners and businesses find Bakeris when they are comparing trusted roofing companies in Des Moines and Central Iowa.
FAQ
Storm & Hail Damage FAQ
How do I know if my roof has hail damage?
How soon after a storm should I get an inspection?
What's a storm chaser and why should I avoid them?
Do you provide storm damage roof repair in Des Moines after hail and wind?
Will Bakeris meet my insurance adjuster on-site?
Where in Iowa do you handle hail damage roof repair?
What is the difference between hail damage and normal shingle wear?
Areas We Serve
Storm & Hail Damage in Des Moines & Central Iowa
We provide storm & hail damage services across the Des Moines metro and surrounding communities. Click your city below for local details.
Related Services
You Might Also Need
Emergency Roof Repair
Active leak, wind-lifted shingles, or storm damage in Des Moines? Same-day tarping and leak repair during business hours, when safe access allows.
Roof Replacement
Complete tear-offs and expert installation using premium Owens Corning, Tamko, Malarkey, GAF, CertainTeed, and Stone Coated Metal. Backed by our 50-year system warranty.
Roof Repair
From missing shingles to complex leaks, our rapid-response repair teams fix the problem before it destroys your home interior.
Roof Inspections
Trained technician inspections that identify problems early. Perfect for storm damage assessment, home purchases, and annual maintenance.
Ready to Get Started?
Contact our team today for a free storm damage inspection. We'll document hail or wind damage and explain the construction options for repair or replacement. Whether to file a claim is your decision; coverage decisions stay with your insurer.